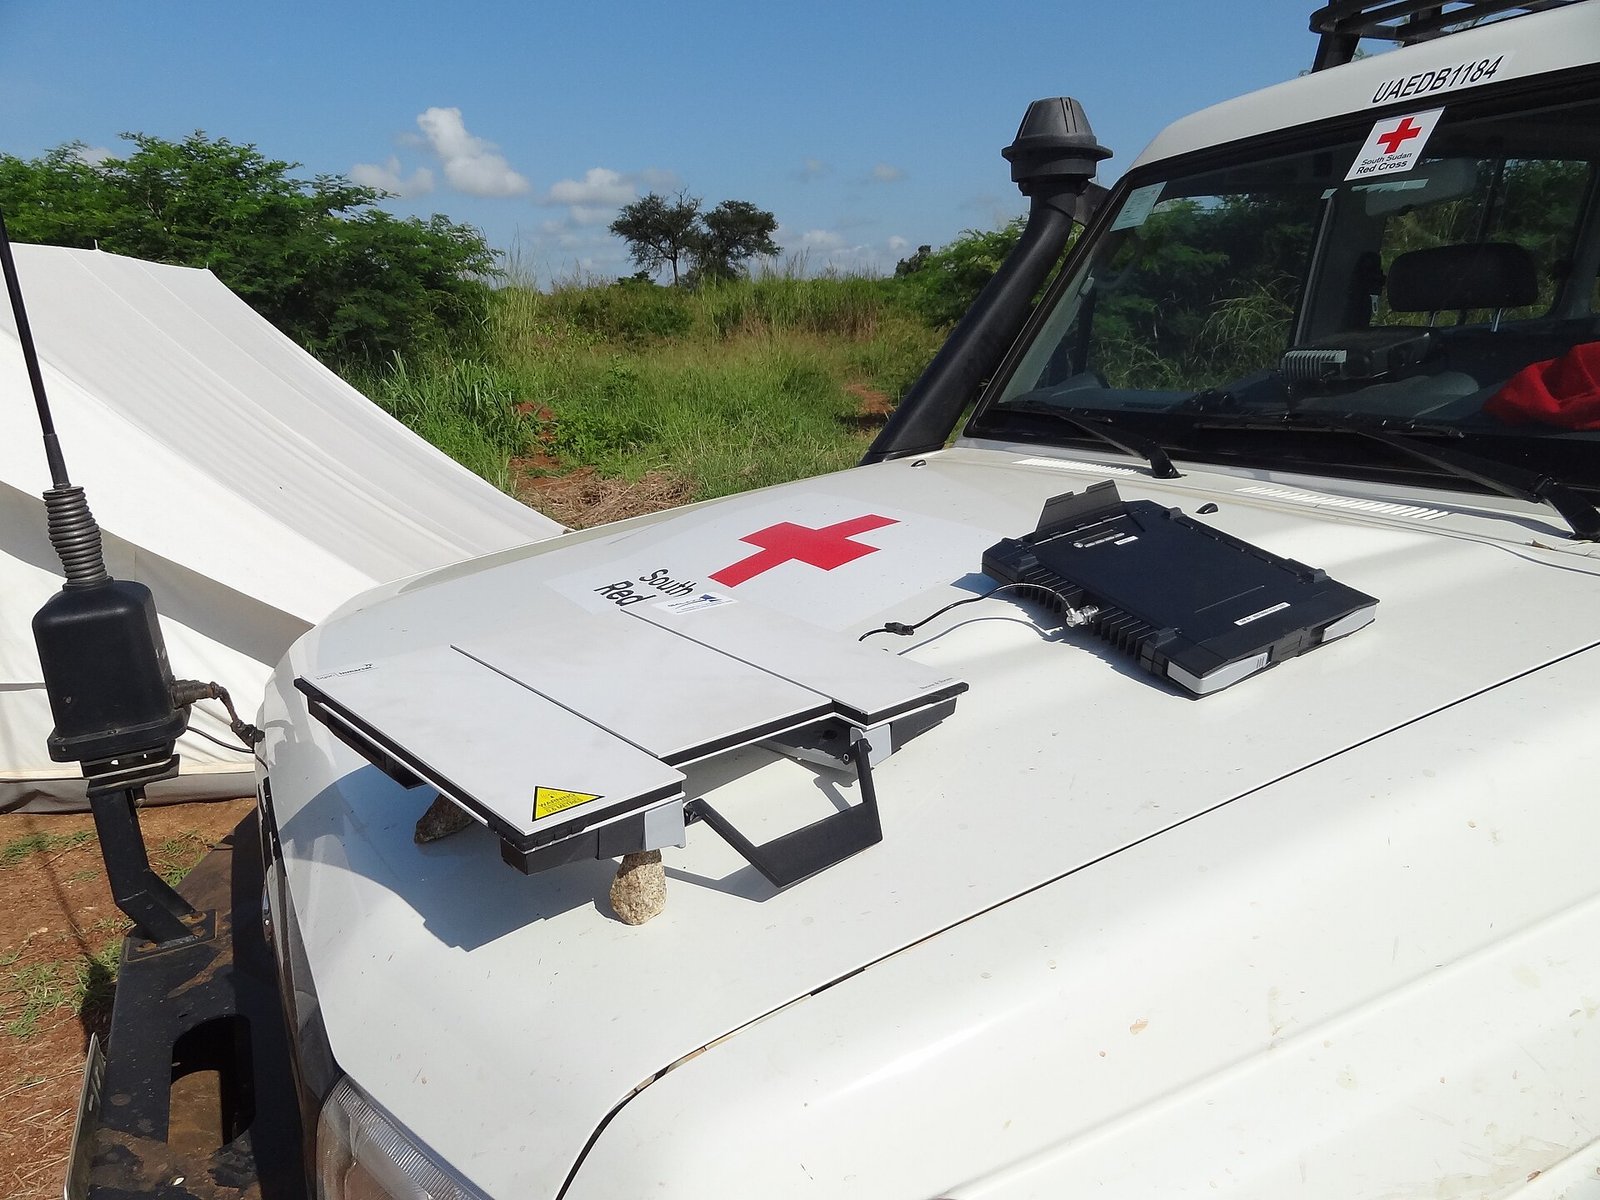
Photo: Miles.world / Wikimedia Commons, CC BY-SA 4.0
Africa’s satellite internet market is being shaped as much by local licensing and distribution deals as by the satellites orbiting above the continent.
Control is moving closer to the customer
Low-Earth-orbit broadband networks promise to connect homes, businesses and public services beyond the reach of fibre and mobile towers. Yet the critical commercial question is increasingly who is authorised to sell, install and support those services locally.
DGBN has also reported on Africa’s growth needs industrial giants and tech risk-takers, ISS argues.
A new analysis by TechTrendsKE highlights how licensing rules, wholesale agreements and telecoms partnerships are determining the route satellite capacity takes to African users. That can mean direct-to-consumer sales by an operator, resale through a licensed internet provider, or satellite capacity used behind the scenes to extend a mobile network.
In Uganda, Starlink’s market entry has already brought local distributors into the picture. Paratus Uganda began commercial Starlink sales in August, while MTN Uganda launched its Starlink for Business offer in October. The country’s regulator says Starlink’s licence permits infrastructure-sharing arrangements with other licensed operators, potentially expanding service in underserved areas.
Regulation decides the business model
The contest is not simply between Starlink, Eutelsat OneWeb and Amazon Leo. National regulators can determine whether a satellite firm sells directly, works through a domestic partner or cannot enter at all.
South Africa illustrates the stakes. Amazon Leo has agreed to work with local internet provider Herotel, which is expected to handle sales, installations and customer support when commercial service begins in 2027. Amazon supplies the satellite network, while the South African company retains the frontline relationship with customers.
For more context, read DGBN’s coverage of Côte d’Ivoire Radio-Frequency Stations Rise as AIGF Expands Spectrum Oversight.
By contrast, Starlink’s path in South Africa has been constrained by licensing and ownership requirements. The country’s communications regulator has set out that satellite operators must meet specific electronic communications and spectrum licensing conditions before operating legally.
Kenya is also refining its approach. The Communications Authority has published a draft Satellite Frequency Licensing Framework for consultation, signalling that spectrum access and regulatory obligations will become more clearly defined as demand rises.
Why it matters for African consumers and businesses
For Black communities across Africa, the outcome will affect more than download speeds. Distribution models influence prices, device availability, installation support, consumer protection and whether African-owned telecoms businesses share in the value created by new connectivity networks.
Local partnerships can help satellite providers reach remote communities using established sales channels and technical teams. They can also strengthen domestic operators’ roles in a market that might otherwise be controlled from abroad. But exclusive arrangements or limited wholesale access could concentrate power among a small number of firms.
Eutelsat OneWeb has already pursued a distributor-led approach in parts of sub-Saharan Africa, including agreements with NEC XON and Angola’s MSTelcom. In Nigeria, regulatory records show both Starlink and OneWeb-related services operating within a formal licensing environment.
Related DGBN reporting includes Tinubu pledges pension guarantee and healthcare support for Nigerian retirees.
The next phase of Africa’s satellite internet boom will therefore be decided not only in space. It will be settled in regulatory offices, commercial negotiations and the local networks that stand between global satellite companies and African customers.